How to Track Post-Dated Cheques and Returns in India
A post-dated cheque tracker is one register that holds every cheque you receive and every cheque you issue, with its date, amount, bank, presentation date and status. Each row triggers a reminder a few working days before the date it will be presented. When a cheque comes back, the return memo is logged against the same row and passed to your company's counsel the same day. You can build the first version in a spreadsheet or in your accounting software, then connect reminders through email or WhatsApp. The automation handles the calendar and the paperwork trail. A person still decides what to do when a cheque is not paid.
In short
- Keep one register for cheques received and cheques issued, tied to the invoice or ledger.
- Set the reminder a few working days before each presentation date and assign it to a role, not a person.
- Log every return memo the same day and send bounces to counsel with the 30-day date visible.
- Check Positive Pay submissions for cheques of ₹50,000 and above, and confirm your bank's current rule.
- Automate the calendar and paperwork, but keep the legal decision and the review of OCR output with people.
What the register has to hold
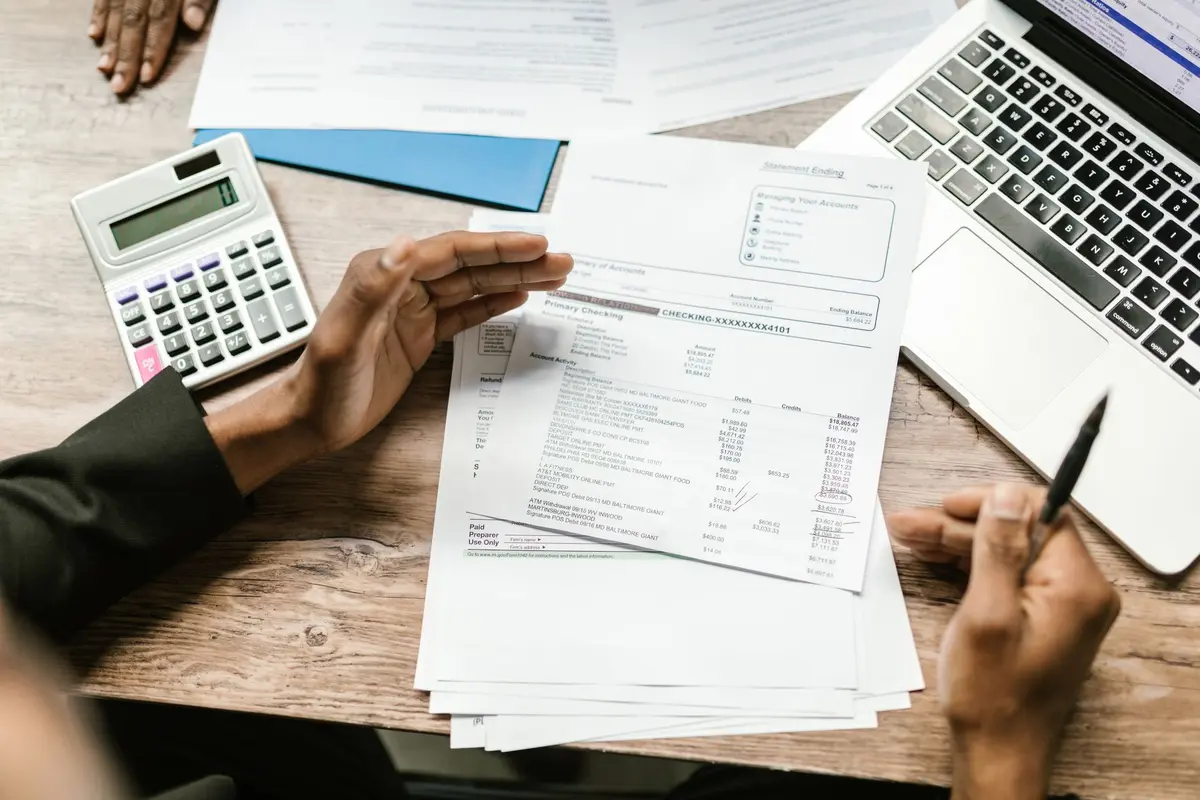
Most businesses already have the cheques. What they lack is a single place that shows what is coming, what has cleared and what has come back. A useful register has two sides. The first side lists cheques you have received from customers. The second lists cheques you have issued to suppliers, landlords, staff advances or lenders. Keep them on separate tabs but tie them to the same invoice or ledger reference, so that a cheque is never tracked in isolation.
Each row needs the cheque number, the drawer and drawee bank, the amount in figures and words, the date written on the cheque, the date you plan to deposit or the date you expect the other side to present it, the invoice it pays, and the current status. Add two fields that people forget. The first is the date you last confirmed the cheque with the other party. The second is, for cheques you issue, the date you submitted the cheque details to your bank under the Positive Pay System, if the amount qualifies.
The status field should only take a few values: received, deposited, cleared, returned, replaced, stopped. Keeping the list short makes the monthly review fast and stops people inventing new labels.
Why this costs money
A post-dated cheque is a promise to pay on a future date. The cost comes from losing track of that date. If a receivable cheque is deposited late, cash arrives late. If it is deposited without anyone checking the funding, it may come back. If it comes back and nobody logs the memo, the clock for a legal demand can run out unnoticed.
Under the Negotiable Instruments Act, 1881, the payee must send a written demand notice within 30 days of receiving the bank's information about the dishonour. The drawer then has 15 days from receipt of that notice to pay. Under Section 138 of the same Act, a dishonour in these circumstances can lead to imprisonment of up to two years, a fine of up to twice the cheque amount, or both. Those are the stakes if a return is missed. Counsel handles the notice and any complaint, but the company has to produce the return date and the memo on time.
A cheque is also valid only for a limited period after its date. A cheque that is not presented within its validity period cannot be used for a Section 138 claim, so an old cheque sitting in a drawer can quietly become worthless.
We could not find a recent published figure for how many staff hours a typical company spends chasing post-dated cheques, nor for the average value lost to late or bounced cheques in India. We have not put a number on either. The practical test is to count the hours your finance team spends on cheque follow-up for one month, and to list every cheque that came back in the last year with its cost in time and money.
Manual way and automated way
The table below shows where the work changes hands. The left column is what a finance or operations person does by hand today. The right column is what runs without them.
| Task | Manual way | Automated way |
|---|---|---|
| Logging a new cheque | Someone types it into a sheet, often days after receipt | A photo or PDF of the cheque is read by OCR and a row is created for review |
| Reminder before presentation | Someone remembers, or a sticky note does the job | A calendar rule and a message to the owner and the bank team a set number of working days ahead |
| Confirming with the customer | A phone call or a chat message typed from scratch | A pre-approved WhatsApp or email message sent from the register |
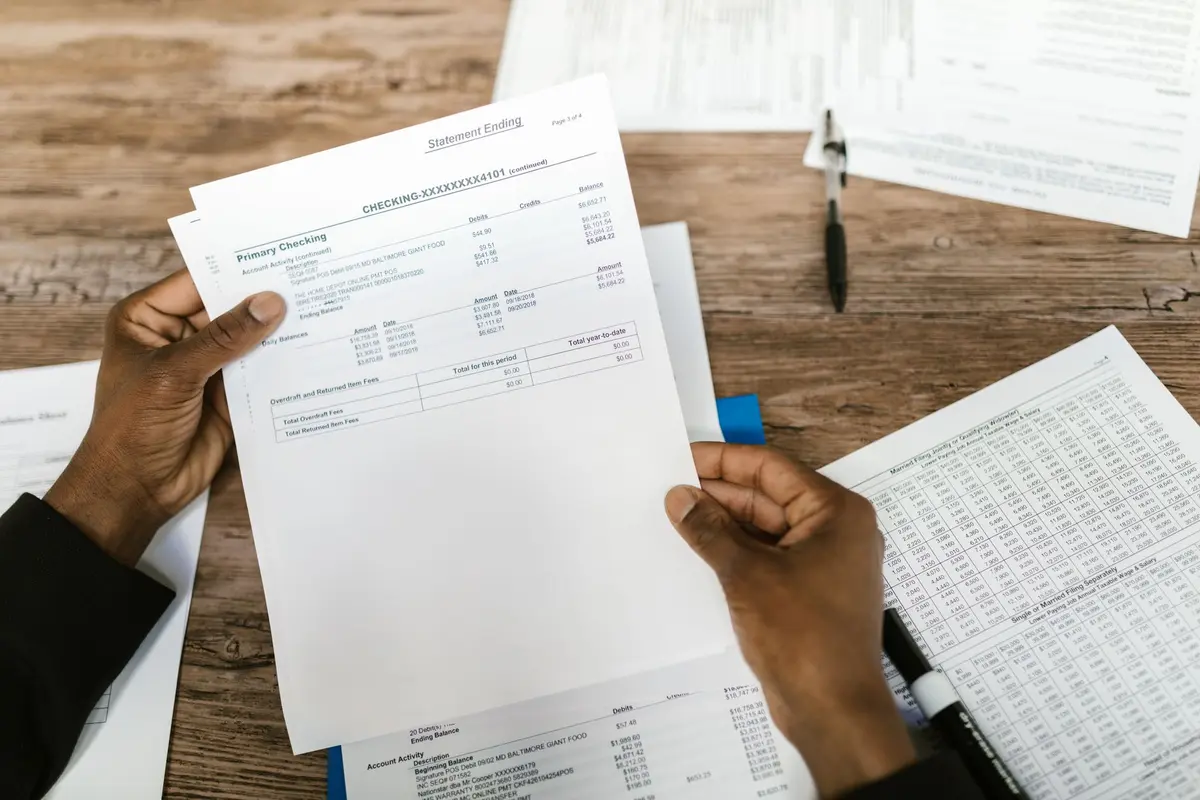
| Recording a return memo | The memo sits in an inbox or a file cabinet | The memo is picked up from the email inbox, matched to the cheque number and marked returned |
| Routing a bounce | Someone forwards it when they remember | Flagged to counsel the same day, with the 30-day date printed on the row |
| Month-end check | Manual comparison with the bank statement | Register compared with the bank statement export, and mismatches listed for a person to review |
The automated column is not free of human work. Someone still checks OCR output, approves messages and reads every return memo that the system could not match.
How to set it up, step by step
- Start with a clean list. Export every open cheque you hold and every cheque you have issued that has not cleared. Mark the stale ones and ask counsel whether any need separate handling before you enter them.
- Build the register in a shared spreadsheet or in the sub-ledger of your accounting package. Tally and Zoho Books are common choices in India. Pick one place of record and do not keep a parallel list in a notebook.
- Set a reminder rule. Three working days before each presentation date works for most firms. Send the reminder to the person who owns the customer or supplier, and copy the bank or treasury contact who will deposit the cheque.
- Connect the customer confirmation. For customers who respond on WhatsApp, use an approved utility template that confirms the cheque number, amount and deposit date. Meta's India rate card for utility messages is listed at ₹0.115 per message, plus 18% GST, effective 1 October 2026. Confirm the category with the provider before you submit any template, because a message filed as marketing costs more and may be refused.
- Capture return memos. Route the bank's return memo to a single shared inbox. An OCR tool or a large language model can read the PDF and pull out the cheque number, date and return reason. A person checks the extracted fields before the row changes to returned.
- Route bounces to counsel. When a row changes to returned, the system should send the return date, the reason and the 30-day deadline to counsel, and nothing more. Counsel decides the notice wording and the channel. The Allahabad High Court has accepted a demand notice sent by email or WhatsApp as valid in a 2024 ruling, but whether your notice uses those channels is a legal decision, not an automation setting.
- Run a monthly match. Export the bank statement for the month, compare it with the register, and list cheques that show as deposited but not cleared, and cleared cheques that the register still shows as open.
For the Positive Pay System, the bank asks you to submit cheque details before you hand the cheque over. The Reserve Bank of India introduced it in 2021 for cheques of ₹50,000 and above, and banks may make it mandatory at ₹5 lakh and above. Thresholds and the way you submit details differ by bank, so check your bank's current rule. Your register should record the date you submitted each cheque's details, because a cheque that was not submitted may be refused.
What breaks and how to prevent it
Most failures are in the data, not the software. The usual ones are below.
- Cheques issued by the wrong entity, or cheques written in a different name from the invoice. The register should not accept a row without a matching invoice reference.
- OCR misreads a cheque number or amount. Require a person to confirm every new row before it is treated as final.
- Return memos arrive in a format the system does not recognise. Keep a manual review queue and check it every working day.
- A customer stops payment or replaces a cheque. Ask the team to update the status the same day and record the replacement number.
- Reminders go to the wrong person when staff leave. Assign each row to a role, not a name.
- Notices are sent from the register without counsel having reviewed them. Keep the legal step outside the automation.
Automation cannot read the intent behind a bounce. It cannot tell you whether the customer is in difficulty, whether a dispute is genuine, or whether a settlement is better than a notice. It also cannot make the bank send a return memo faster.
When not to automate
If you receive or issue only a handful of post-dated cheques a month, a spreadsheet with a recurring calendar entry is enough. The setup, the template approvals and the checking would cost more time than they save. The same is true if your customers are moving to bank transfers, UPI or NACH mandates and cheques are disappearing from your books. Build the register, but do not build a messaging flow for a product you are about to retire.
Do not automate the legal decision. Anything involving a notice, a complaint or a settlement belongs with counsel. Do not let the system send demands on its own, even when the dates line up.
What it typically takes
The first version is a matter of days of setup work for one person who knows the cheque flow well. The slower part is cleaning the open cheques, agreeing the status labels and getting the bank's return memo format into the inbox. Expect the first two month-end matches to find errors. That is normal and it is the reason to keep the review step.
Plan for a short review each month. Look at the cheques due in the next 15 working days, the return memos not yet matched, and the notices sent to counsel. If that review takes more time than the old manual process, the rule set needs tightening, not more people.
Sources
- Cheque Clearing Time in India: CTS Process & RBI Rules
- Discover the RBI's new Real-Time Cheque Clearing system launching in October 2025. Learn how these changes will impact t
- Continuous Clearing and Settlement on Realisation
- Cheque Truncation System
- RBI delays January 3 rollout for 3-hour cheque clearance: What it means
How AiStaffo would automate this
AiStaffo would connect the register to the email inbox where bank return memos arrive and to the WhatsApp Business account used for customer confirmations, so each cheque gets its reminder and each memo is read and matched without someone opening a file. The system would create the row from a scanned cheque, mark it returned when a memo matches, and send the return date and the 30-day deadline to counsel. Your finance lead still confirms new rows, checks flagged memos, decides which customers to call, and passes every bounce to your counsel. Book a free automation audit to see whether a register like this fits your cheque volume and bank setup.
Questions people ask
How long is a post-dated cheque valid in India?
What is the 30-day rule for a cheque bounce notice?
Does the Positive Pay System apply to every cheque?
Can WhatsApp be used to remind customers about a cheque?
Is cheque clearing faster in India now?
Should I use OCR to read cheques and return memos?
Book a free automation audit
Thirty minutes. We look at one process you run every week and tell you exactly what an AI worker would take off your desk, and what it would not.